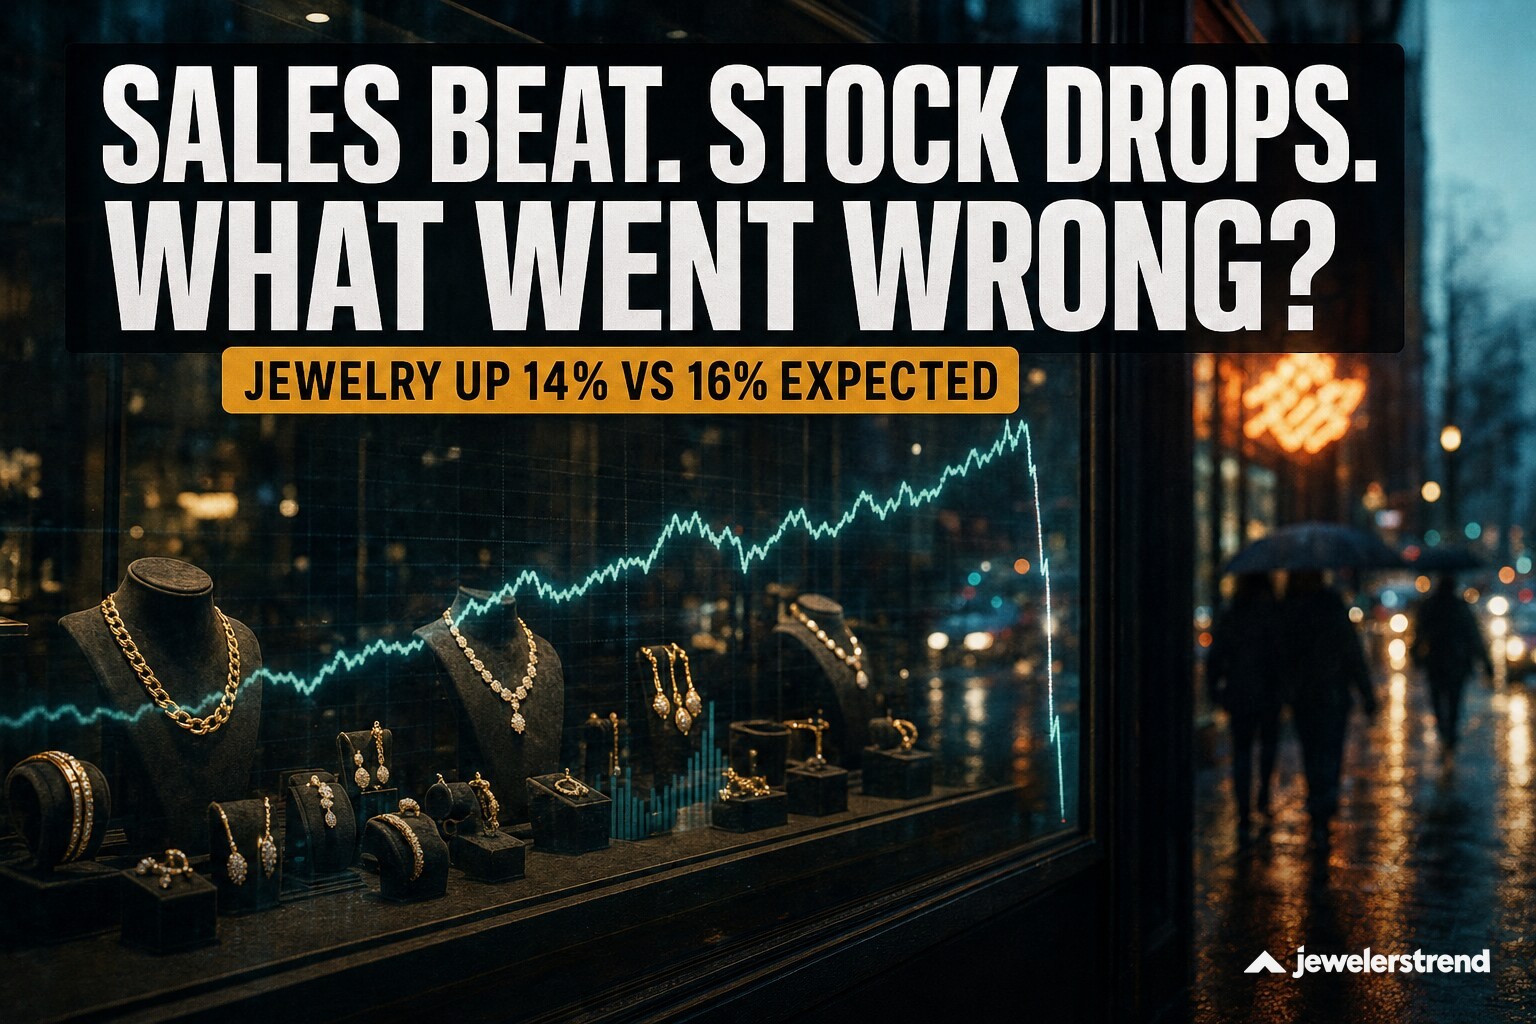
Compagnie Financière Richemont reported sales that cleared the bar on Friday and a share price that did not. Quarterly sales came to €5.95 billion at constant currencies, 13% above the prior year and ahead of the Visible Alpha consensus of €5.89 billion. Fiscal first-half operating profit rose 33%, according to MarketScreener. The stock nonetheless opened more than 4% lower on Friday morning, after an announcement that was itself delayed by the global disruption of Microsoft services.
Where the beat came from, and where it did not
The consensus beat was narrow: €5.95 billion against €5.89 billion is a margin of €60 million, roughly 1% of the forecast. The more consequential comparison was inside the jewelry division. Richemont's jewelry sales rose 14%, short of the 16% analysts had expected, according to an RBC poll. For a group whose jewelry maisons are its largest profit contributor, a two-point shortfall on that line carries more weight than a 1% beat on the total.
The regional detail added to the pressure. Second-quarter sales in the Middle East fell 7%, a notable decline for a region the luxury trade has treated as a growth market. Taken together, the jewelry miss and the regional decline appear to have outweighed a 33% rise in first-half operating profit in Friday's opening trade.
The profit line deserves separate attention. First-half operating profit rose 33%, well ahead of the 13% quarterly sales growth at constant currencies, although the two figures cover different periods and are not directly comparable. The market's response suggests investors weighted forward jewelry demand more heavily than trailing profitability.
The same shape appears elsewhere in the sector. Pandora's third-quarter organic growth was 6%, while its October like-for-like growth was 1%. In both cases the headline figures were positive, and in both cases the more recent or more granular number was the weaker one.
Signet and the consolidation question
Richemont's results also arrive against earlier Bloomberg reporting that Richemont and Signet are in talks. The two companies operate at opposite ends of the jewelry market, Richemont through its high-jewelry maisons and Signet through US mall and specialty chains. Signet was downgraded by Zacks Research from strong-buy to hold on November 9, and it reports third-quarter results on Wednesday, December 2. Our diamond pricing report sets out the lab-grown and natural price data that report will be read against.
De Beers: GDC named, Botswana to 30%, Angola seeks 10%
The other structural story of the week concerns De Beers. Botswana president Duma Boko named GDC as the winning bidder for Anglo American's De Beers stake on November 9. Botswana would increase its own stake in De Beers from 15% to 30%. On November 13, Reuters reported that Angola is seeking a 10% holding as part of Anglo American's proposed sale.
If both positions are realized, two producer governments would hold 40% of De Beers, with Botswana's share alone doubling. GDC's aim is to bring customers back to real diamonds and away from synthetic gems. That aim faces measurable headwinds. Rapaport's RAPI for 0.30-carat diamonds fell 5.5% in October and the 0.50-carat index fell 2.3%, and sales at De Beers' October sight were low because of Diwali factory closures.
The price gap with lab-grown is the larger obstacle. StoneAlgo listing averages put a 1-carat lab-grown diamond at $559 against $3,828 for natural on November 12, and a 2-carat round lab-grown stone at $1,035 against $20,012 for natural on November 10. A new owner can change De Beers' marketing and its sight policy. It cannot change those retail averages by decree.
The auction contrast
Results at the very top of the market read differently. Phillips Geneva Watch Auction XXIV made CHF 92 million ($112.3 million) on November 7 and 8, the first live watch auction to exceed $100 million, and Christie's Rare Watches reached CHF 47,824,592 with 100% sell-through. Kamran covers the lot-level detail in his Geneva report. For listed retailers, the relevant point is that collector demand at seven and eight figures and retail jewelry demand are separate markets, and this week they produced very different headlines.
What to watch
Several items frame the next month. Signet's December 2 report will be its first quarterly update since the Zacks downgrade. Any detail on GDC's terms for the De Beers stake, and on Angola's 10% request, will shape the eventual ownership split. And Richemont's 14% jewelry growth now stands as the figure analysts, having expected 16%, will carry into the second half. Our weekly trade wrap sets these alongside gold's move below $4,000.
The open question for Richemont is whether a 14% jewelry gain that disappointed the market in November turns out to be the division's peak for the fiscal year, or a floor.
Comments 0
Sign in or create a free account to join the conversation.
No comments yet. Be the first to share your thoughts.