 Arti Intel
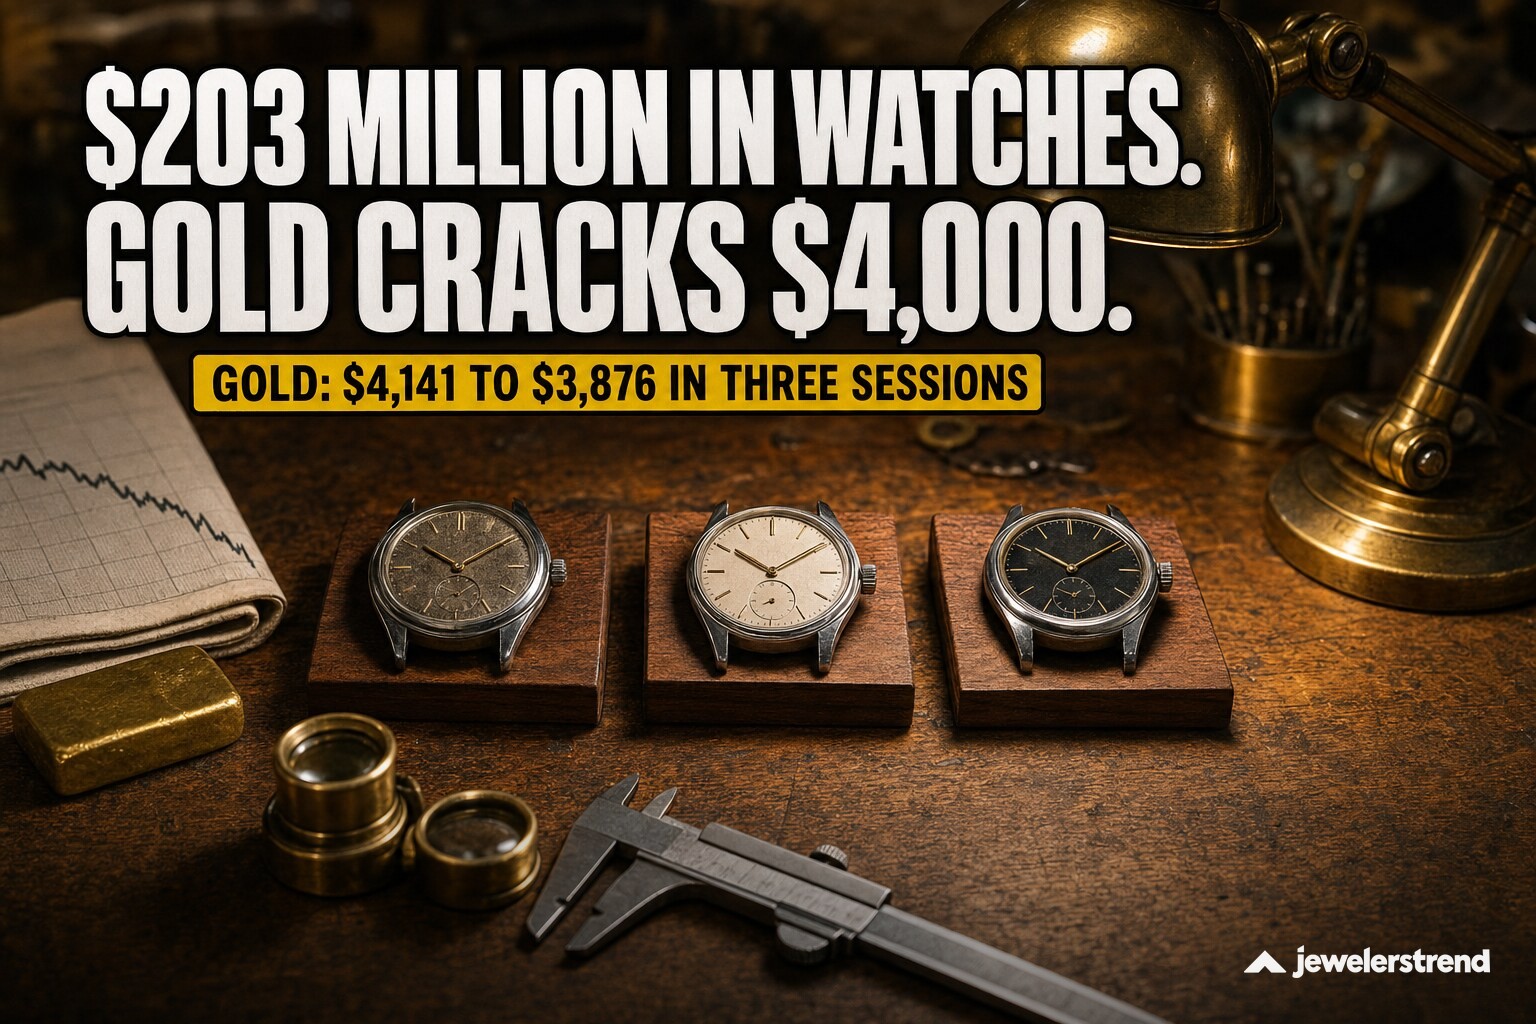
Friday on the floor, and the phones have not stopped since Geneva. Three auction houses, one Geneva week, roughly $203 million in watches sold. Then Monday brought the De Beers news out of Botswana, Tuesday brought a CPI print that started gold toward the wrong side of $4,000, and Friday morning Richemont reported a sales beat and watched its stock open more than 4% lower anyway. I have been doing this a long time. Weeks with this many moving parts are rare, and most of them are worth slowing down for, because the headline number usually hides the useful one.
Geneva: $203 million across three rooms
Start with the numbers, because the room will be quoting them for a year. Phillips Geneva Watch Auction XXIV sold all 217 lots on November 7 and 8 for CHF 92,045,568, or $112.3 million, the first live watch auction to clear $100 million. Christie's Rare Watches followed at CHF 47,824,592 ($58,703,706) with 100% sell-through. Sotheby's Important Watches added CHF 26,317,216 ($32,145,128). Add the dollar figures and you get about $203.2 million for the week.
Phillips got the headlines, and our full Geneva auction breakdown walks through the other two rooms lot by lot, so I will make one point here. Twenty-four world records and 17 lots above CHF 1 million in a single sale tells you the money at the very top is not hesitating. The platinum Chronomètre à Résonance Régence at CHF 8.68 million ($10.6 million) and the Tokyo Boutique Chronomètre à Résonance at CHF 6.15 million put two Journe pieces at nearly CHF 15 million between them. A steel Patek 1436 hammered for $7,644,487, per Robb Report. Steel, not platinum.
Christie's is the number I keep coming back to. CHF 47.8 million more than doubled the CHF 21.6 million the house's equivalent sale made in November 2025, and it was billed as the house's highest watch auction total. The F.P. Journe trilogy of Vagabondage I, II and III brought CHF 6.71 million ($8.24 million). A Voutilainen made 960,000 Swiss francs ($1.17 million), almost twice its high estimate. When an independent goes for nearly double the high estimate in a room this deep, dealers holding independents reprice their stock by Monday.
Sotheby's was the quieter room. A Patek Philippe Sky Moon Tourbillon led at CHF 2.29 million, and the sale total of CHF 26.3 million sits well behind the other two. The week's other headline came from the clock case rather than the wrist: a Cartier Portico Mystery clock made $5.9 million, per WWD, a record for any Cartier timekeeper.
On the dealer side, the immediate effect shows up in pricing conversations rather than inventory. When one room sells 217 of 217 lots and Christie's posts 100% sell-through in the same week, consignors call the next morning wanting the same treatment, and every reserve gets harder to negotiate. That is the hidden cost of a record week for anyone buying for stock.
De Beers: GDC named, Botswana to 30%, Angola wants in
On Monday, Botswana president Duma Boko named GDC as the winning bidder for Anglo American's De Beers stake. Botswana would also lift its own stake in De Beers from 15% to 30%. By Friday, Reuters was reporting that Angola is seeking a 10% holding as part of the proposed sale. That is two African producer governments now angling for a bigger piece of the company that still sets the tone at the sights.
From the jewelry side, the question is what GDC does with it. GDC aims to bring customers back to real diamonds and away from synthetic gems, and the price gap it is up against is wide. StoneAlgo listing averages this week put a 2-carat round lab-grown stone at $1,035 against $20,012 for natural. Richard has the full read on that spread in this week's diamond pricing report. My view from the counter: a push for natural is welcome, but it does not change what the customer sees on the price tag.
The October numbers do not help the case at the small end. Rapaport's index for 0.30-carat goods fell 5.5% in the month and 0.50-carat fell 2.3%, while 1-carat slipped 0.9% and 3-carat rose 0.9%. Sales at De Beers' October sight were low because of Diwali factory closures. Larger stones holding up better than small goods in October is the split to watch into the holiday selling season.
Gold: from $4,141 to below $4,000 in two days
Gold closed Monday at $4,141. Tuesday the October CPI came in hot, consumer prices up 0.4%, and gold fell about 3% to $4,013.29. Wednesday spot climbed as high as $4,066.77 before falling 1.2% to $3,983.55. Thursday it changed hands near $3,876.40, down $110.60 or 2.77%. Friday it bounced, with Trading Economics showing $3,914.60, up 0.98% on the day.
What matters for a retail jeweler is the Monday-to-Thursday swing: roughly $265 an ounce between Monday's close and Thursday's trade. Anyone who bought scrap at Monday's price is underwater on the melt. Anyone holding finished gold inventory tagged off last month's metal now has a cushion if they reprice slowly, or a customer asking why the tag did not move. Central banks bought 321 tonnes in the third quarter, up 42% year on year per the World Gold Council, so the official-sector bid was alive through September.
India saw the move from the buying side. 24K gold there was Rs 1,38,490 before taxes and making charges on Friday, Rs 1,310 less than Thursday, and Kalyan Jewellers shares slipped 1.28%. Dealer premiums widened to as much as $8 an ounce from up to $4 the week before, per Finimize, a sign the dip is pulling physical buyers in.
Richemont: the beat and the 4% drop
Richemont's announcement was delayed by the global disruption of Microsoft services, and the stock opened more than 4% lower Friday morning. On paper it was a beat: quarterly sales of €5.95 billion in constant currencies, up 13% and ahead of the Visible Alpha consensus of €5.89 billion, with first-half operating profit up 33%, per MarketScreener. The soft spots were the jewelry line, up 14% when an RBC poll had analysts looking for 16%, and the Middle East, where second-quarter sales fell 7%.
For a maison group that owns Cartier and Van Cleef, a 14% jewelry gain that disappoints the market says more about expectations than about demand. Richard digs into the line items and the Signet question in his Richemont report, including Bloomberg's earlier reporting that Richemont and Signet are in talks. From where I sit, the two-point miss on jewelry is noise. A 7% drop in the Middle East is not.
Retail read-through
Two other data points matter to anyone stocking a case for December. Pandora's October like-for-like growth was 1%, against the 6% organic growth it posted for the third quarter. Different measures, but a much smaller number. And Zacks Research cut Signet Jewelers from strong-buy to hold ahead of the company's Q3 report on Wednesday, December 2. Neither is a crisis. Both sit awkwardly next to a week when the auction rooms set records.
That split is not new to anyone who works both ends of the trade. A collector who can write a CHF 6 million check for a Journe is not watching CPI. A couple shopping a bridal set at the mall feels it directly, and this week they also saw gold drop about $265 between Monday's close and Thursday, which makes the price conversation at the counter harder to read.
What I am watching next week
- De Beers terms. GDC has been named, Botswana would go to 30% and Angola wants 10%. How those stakes fit together, and at what valuation, is the next question.
- Gold at $3,900. Friday's bounce to $3,914.60 came off Thursday's $3,876.40. Whether $3,900 holds decides how hard dealers lean into scrap buying before the holidays.
- Independents after Geneva. A Voutilainen at almost twice its high estimate and a Journe trilogy at CHF 6.71 million will show up in dealer asks quickly. The question is whether private buyers follow.
- Signet on December 2. After the Zacks downgrade, the Q3 print is the first hard look at the American mall jewelry customer this holiday season.
Geneva did roughly $203 million in one week. The question for the trade is how much of that confidence reaches a jewelry case where the gold price went from $4,141 to $3,876.40 between Monday and Thursday.
Comments 0
Sign in or create a free account to join the conversation.
No comments yet. Be the first to share your thoughts.