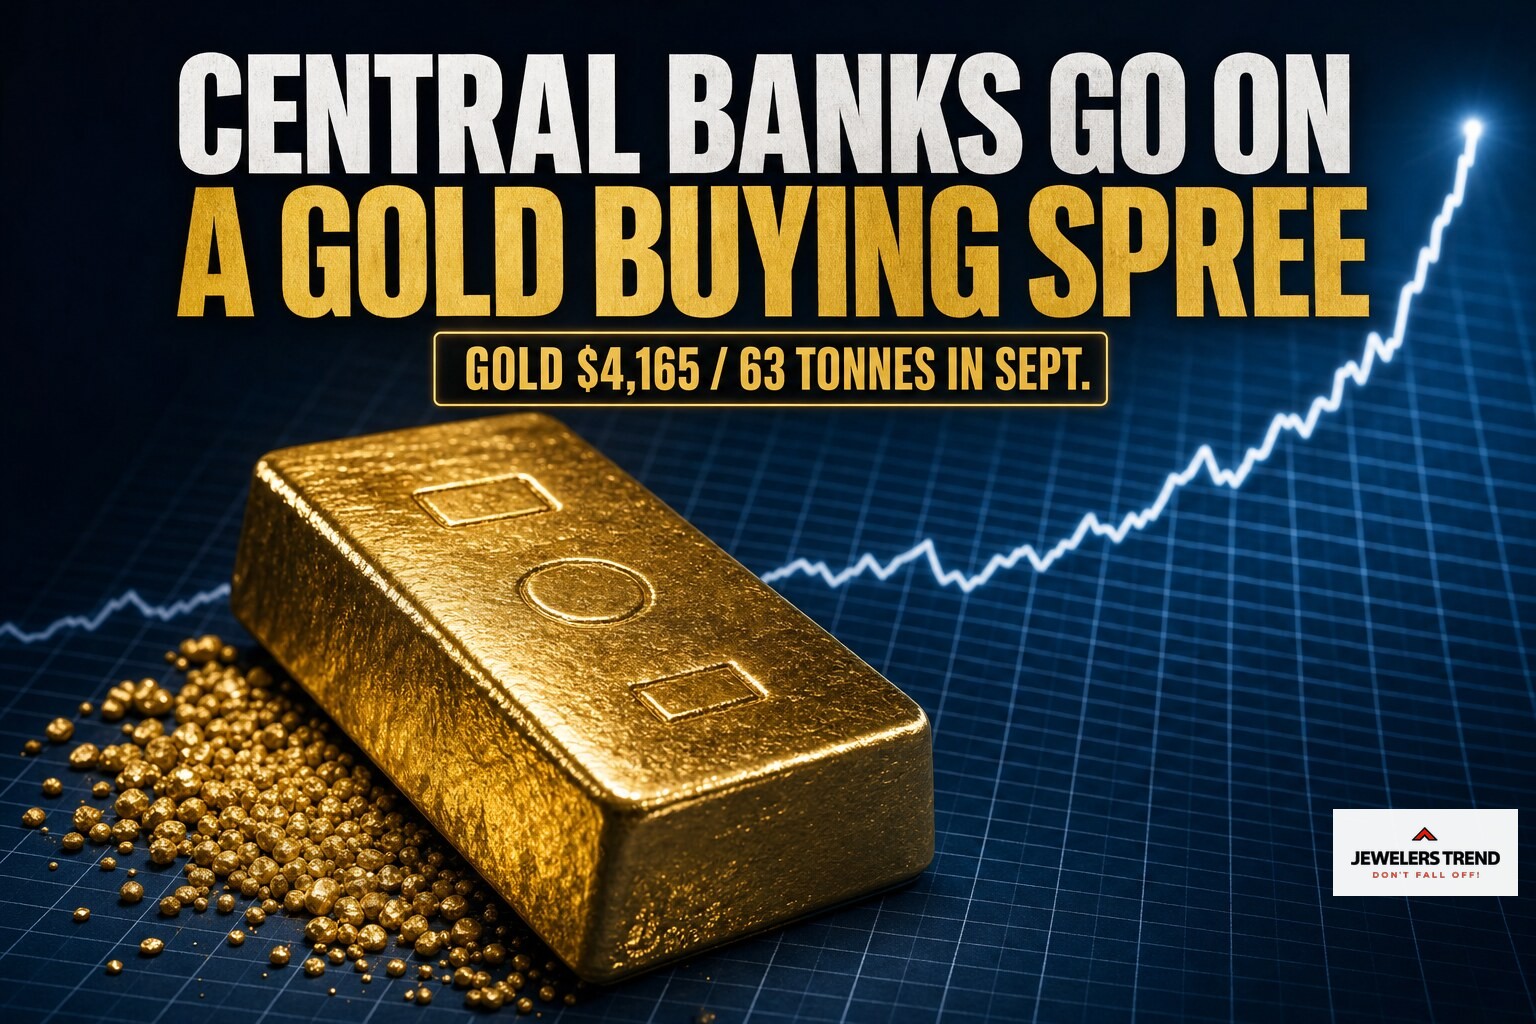
Gold spent the week doing what it has done all year: climbing on relentless official-sector demand while everything else in the luxury complex wobbled. Spot printed 4,165.55 per ounce at 9:00 a.m. Eastern on Thursday, October 16, the high mark of a volatile but upward week.
The week's tape
The move was not a straight line. At 9:00 a.m. Eastern on October 14, gold was 4,095 per ounce, an 87-dollar downtick from the same time the day before. By 9:10 a.m. On October 15 it had rebounded to 4,147, a 52-dollar rise in a single session, though still 40 dollars below where it traded a year earlier. Thursday's 4,165.55 extended that bounce. Spot had slipped 0.3% to roughly 4,158 on October 13 before the recovery, so the net of the week was a dip bought aggressively and a grind back toward 4,200.
For a bullion desk, the lesson of the week is that the dips are shallow and bought fast. An 87-dollar drop on Tuesday was fully reversed and then some by Thursday. That is not the behavior of a market looking for an excuse to sell. It is the behavior of a market where a large, price-insensitive buyer is underneath every pullback.
Who the buyer is
That buyer is the official sector, and the September data makes it plain. Central banks bought about 63 tonnes of gold in September, the most since November 2024. China's central bank alone added 21 tonnes, described as its largest monthly purchase in three years. The pace had already been building: central banks reported 39 tonnes of net buying in August and 170 tonnes through August, with China adding 20 tonnes in August and Poland and Uzbekistan each adding eight.
Step back to the half-year view and the scale is clear. Official institutions purchased an estimated 345 tonnes in the first half of 2026, including 289 tonnes in the second quarter alone. The forecast calls for 720 tonnes across the full year. When buying runs at that pace month after month, regardless of whether spot is at 4,095 or 4,165, it puts a firm structural floor under the metal that short-term traders keep underestimating.
It helps to see where the half-year total came from. Official institutions bought an estimated 289 tonnes in the second quarter alone on the way to 345 tonnes in the first half, then kept the pace through the summer with 39 tonnes in August and 170 tonnes booked through August. China did much of the recent lifting, adding 20 tonnes in August before its 21-tonne September purchase, while Poland and Uzbekistan each added eight tonnes in August. This is not one buyer or one month. It is a broad, sustained official bid, and that breadth is what makes the 720-tonne full-year forecast credible rather than aspirational.
What it means for refiners and the trade
For refiners and bullion dealers, a market held up by central-bank accumulation rather than speculative flows is a steadier one to work. The flows are predictable in direction even when the daily tape is choppy, and demand of that size keeps premiums and fabrication orders firm. It also keeps gold decoupled from the luxury-equity story that dominated headlines this week, where European luxury shed roughly 350 billion dollars in market value and LVMH missed its quarter, a split I walked through in the week's wrap. Gold does not trade on handbag volumes.
There is a second-order effect worth watching for anyone who works both metal and stones. A firm gold price supports the hard-asset case broadly, and it lands at the same moment the diamond market is firming from the bottom, a dynamic I covered in the diamond recap. When both metal and natural stones firm together, the store-of-value narrative gets easier to make at the counter.
The setup into year-end
Add it up and the structure is straightforward. Spot is at 4,165.55 and climbing, dips are being bought within a session or two, central banks bought 63 tonnes in September alone and are tracking toward 720 for the year, and China just posted its biggest monthly purchase in three years. The only soft data point is that gold still sits 40 dollars below where it traded a year ago, a reminder that this run is recovering ground as much as breaking new highs. The question into year-end is whether official buying keeps pace with the 720-tonne forecast, because that figure, more than any technical level, is what the floor under 4,100 is built on.
Comments 0
No comments yet. Be the first to share your thoughts.